Best Landlord Insurance Companies for BRRRR Properties
Landlord insurance is not always straightforward for a BRRRR property.
A finished rental may qualify for a standard landlord policy. A vacant property, heavy renovation, short-term rental, small multifamily building, or LLC-owned property may need more review before an insurer will write coverage.
The company name is only the starting point. A useful quote should show the legal insurance company, policy type, coverage limits, deductible structure, vacancy terms, renovation limits, loss-of-rent coverage, water coverage, theft and vandalism language, and liability limits.
This comparison covers six landlord insurance companies and agencies that real estate investors may see when shopping for rental-property coverage. It is not a price ranking. Premiums vary too much by address, property condition, roof age, claims history, occupancy, construction type, deductible, and state.
How This Comparison Was Researched
This article uses official company pages, current product descriptions, licensing information, and third-party insurance resources.
Company pages were used to confirm whether each provider offers landlord or rental-property coverage, what property types it publicly discusses, how quoting works, and whether the provider references vacant, renovation, loss-of-rent, liability, or specialty property coverage.
We also used the NAIC Consumer Insurance Search as a verification tool. The NAIC can help identify the legal insurance company behind a policy and review complaint information reported through state insurance regulators.
We used AM Best as a financial-strength resource. AM Best ratings help evaluate an insurer’s ability to meet policy obligations. They do not tell you whether a specific claim will be covered under a specific landlord policy.
For large national insurers, NerdWallet’s home insurance review hub provides background on financial strength, complaint data, coverage options, discounts, claims processes, and digital tools. These are homeowners-insurance reviews, not landlord-policy reviews, so they should be used as company-level context only.
We did not use online customer comments as a basis for ranking the companies. Reviews can be useful for spotting service themes, but they are too uneven to prove how a future landlord claim will be handled.
Compare the Policy Before Comparing the Premium
A low annual premium may be perfectly reasonable. It may also reflect narrower coverage, higher deductibles, actual cash value settlement, limited water coverage, or vacancy restrictions.
Before comparing price, compare the policy terms.
Useful items to review include:
- Legal insurance company
- Policy type
- Dwelling coverage limit
- Replacement cost or actual cash value
- Liability limit
- Loss-of-rent or fair rental income coverage
- Vacancy language
- Renovation or construction restrictions
- Water damage limits and exclusions
- Theft, vandalism, and malicious mischief coverage
- Tenant damage language
- Wind, hail, hurricane, or named-storm deductible
- Ordinance and law coverage
- Other structures coverage
- Landlord-owned personal property coverage
- LLC or entity ownership eligibility
- Mortgagee and additional insured wording
The declarations page and policy endorsements matter more than the quote summary.
Six Landlord Insurance Companies to Compare
Steadily
Steadily offers landlord insurance for single-family rentals, multifamily properties, condos, accessory dwelling units, short-term rentals, and vacant or restoration properties. Its public coverage pages discuss property damage, liability, loss of rent, water damage, storm and hail, vandalism, and burglary. Steadily also states that coverage is available in all 50 states, subject to underwriting and state availability.
When reviewing a Steadily quote, confirm the underwriting company, policy type, covered perils, vacancy terms, renovation terms, deductible structure, and loss-of-rent limit. If the property is vacant, being repaired, or held in an LLC, make sure those facts appear correctly in the quote before binding coverage.
View Steadily landlord insurance
Obie
Obie offers landlord insurance through an online quote process for real estate investors, landlords, and property managers. Its site references single-family rentals, multifamily properties, and investor-owned rental housing. Obie operates as an insurance agency, so the underwriting carrier listed on the quote and policy documents should be reviewed separately from the Obie brand.
When comparing an Obie quote, check the legal insurer, property type, covered perils, vacancy language, renovation language, liability limit, and loss-of-rent coverage. If the property is undergoing construction or a larger rehab, describe the actual work being performed instead of treating the property only as a future rental.
State Farm
State Farm offers rental home, rental condo, and apartment-owner insurance through its agent network. Its rental-property materials discuss property damage, injury and liability claims, and possible loss of rental income after covered property damage. It also notes that accidental tenant damage may be covered in some situations, while intentional damage and normal wear are often excluded.
When speaking with a State Farm agent, review current occupancy, planned rental use, ownership name, LLC ownership if applicable, renovation work, tenant-damage language, loss-of-income terms, deductibles, and whether the property requires a rental dwelling policy instead of a homeowners policy. Agent-led quoting may be useful when the property has details that do not fit a simple online form.
View State Farm rental-property insurance
Allstate
Allstate offers landlord insurance through its online quote process and agent network. Its landlord materials describe dwelling protection, liability coverage, medical protection, and fair rental income. Fair rental income generally applies when a covered loss makes the property uninhabitable; it is not coverage for ordinary vacancy, tenant nonpayment, or a slow leasing period.
When comparing an Allstate quote, review dwelling coverage, liability limits, fair rental income terms, tenant-damage language, deductibles, exclusions, and rental type. Long-term rentals, short-term rentals, house hacking, and mixed personal-use situations should be described clearly during the quote process.
View Allstate landlord insurance
American Family Insurance
American Family offers landlord insurance with building coverage, rental payment loss coverage after covered damage, general liability, medical expense coverage, flood-insurance access, and umbrella liability options. The company supports both online quoting and agent-assisted quoting.
Availability is the first item to check because American Family does not operate in every state. If coverage is available, compare the building limit, loss-of-rent terms, liability limit, umbrella eligibility, flood option, ownership requirements, vacancy terms, and repair restrictions.
View American Family landlord insurance
Foremost
Foremost offers landlord and rental home insurance for one-to-four-family rental dwellings. Its landlord materials discuss replacement cost, agreed loss settlement, liability coverage, actual cash value, loss of rents, service line coverage, equipment breakdown, other structures, and package options. Foremost also publishes information for vacant-property coverage.
When comparing a Foremost quote, review the settlement type, selected package, optional coverages, vacancy handling, deductible structure, loss-of-rent terms, and whether the property can move between vacant and rental use under the applicable policy. Foremost often works through agents, which may help when comparing landlord, vacant, and specialty property options together.
View Foremost landlord insurance
Coverage Details That Can Change the Value of a Quote
Replacement Cost vs. Actual Cash Value
Replacement cost and actual cash value can produce very different claim payments.
Replacement-cost coverage generally pays based on the cost to repair or replace covered property with new property of similar kind and quality, subject to policy terms and limits.
Actual cash value usually subtracts depreciation for age and condition. The premium may be lower, but the claim payment may also be lower.
For an older BRRRR property, this distinction can affect roofing, flooring, cabinets, appliances, HVAC equipment, and other major building components.
Vacancy Language
Vacancy can change coverage.
Some policies limit or exclude certain losses after a property remains vacant for a stated number of days. Others may distinguish between vacant, unoccupied, under renovation, between tenants, or held for sale.
A property with no tenant, no furniture, disconnected utilities, and active renovation work may be treated differently from a furnished rental between leases.
Read the vacancy definition before assuming the policy covers the project timeline.
Renovation and Construction Work
Insurance companies do not treat every repair the same way.
Painting, flooring, appliance replacement, and minor repairs may fit within one underwriting category. Structural changes, roof replacement, electrical work, plumbing replacement, additions, or a gut rehab may require different coverage.
A landlord policy may not be the right form for a property under heavy construction. Builder’s risk or vacant renovation coverage may be required depending on the scope of work.
Water Damage
Water losses are often more complicated than they appear.
A sudden pipe break, sewer backup, flood, groundwater intrusion, long-term leak, roof leak, and frozen pipe can fall under different parts of a policy. Some require endorsements. Some may be excluded.
Older rental houses often have aging plumbing, old roofs, drainage problems, or periods without regular occupancy. The water-damage language should be reviewed before comparing price.
Theft, Vandalism, and Tenant Damage
Theft, vandalism, tenant damage, and ordinary wear are separate issues.
A stolen air-conditioning condenser, vandalized vacant house, broken interior door, damaged flooring, and worn carpet may not receive the same treatment.
The quote should clarify whether theft, vandalism, malicious mischief, accidental tenant damage, and landlord-owned personal property are covered.
Loss of Rent
Loss-of-rent coverage is not general income protection.
It usually applies when a covered physical loss makes the rental uninhabitable. The policy may limit the payment period, total amount, or covered causes of loss.
It normally does not cover tenant nonpayment, leasing delays, market vacancy, or a refinance that takes longer than expected.
Ordinance and Law Coverage
Older rental properties may need code upgrades after a covered loss.
A basic property policy may not pay every cost required to demolish damaged portions, remove debris, or rebuild to current code. Ordinance and law coverage can address some of those costs, subject to its own limits.
This can matter for older housing stock where electrical, plumbing, stairs, railings, windows, or structural elements no longer match current requirements.
Liability Coverage
Landlord liability coverage applies to certain injury or property-damage claims connected to the rental property.
The quote should show the per-occurrence limit and any aggregate limit. If an umbrella policy is involved, the underlying landlord policy must usually meet the umbrella insurer’s minimum liability requirements.
Liability coverage does not fix a weak property policy. It is a separate part of the insurance review.
A Practical Way to Compare Quotes
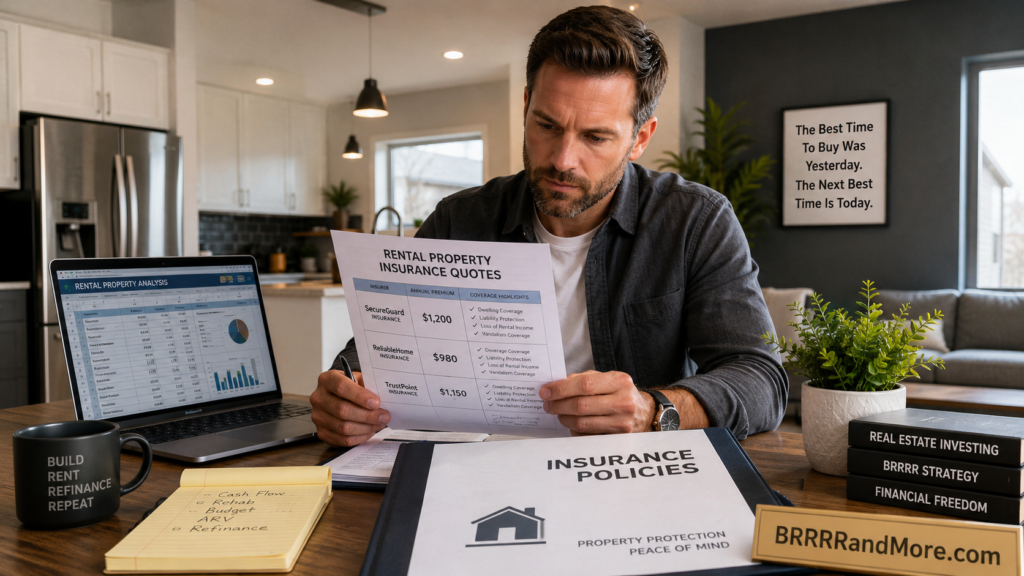
A simple spreadsheet can make insurance quotes easier to compare.
Create one row for each quote. Add columns for the legal insurer, policy type, dwelling limit, settlement type, liability limit, loss-of-rent coverage, vacancy rules, renovation rules, deductibles, water coverage, theft and vandalism, ordinance and law, required endorsements, and premium.
Put the premium near the end of the spreadsheet, not at the beginning.
This makes the coverage differences visible before the annual cost drives the decision.