BRRRR Due Diligence When a Seller Wants a Fast Closing
This is a hypothetical example based on a common BRRRR acquisition problem. The details are simplified to illustrate negotiation and due diligence.
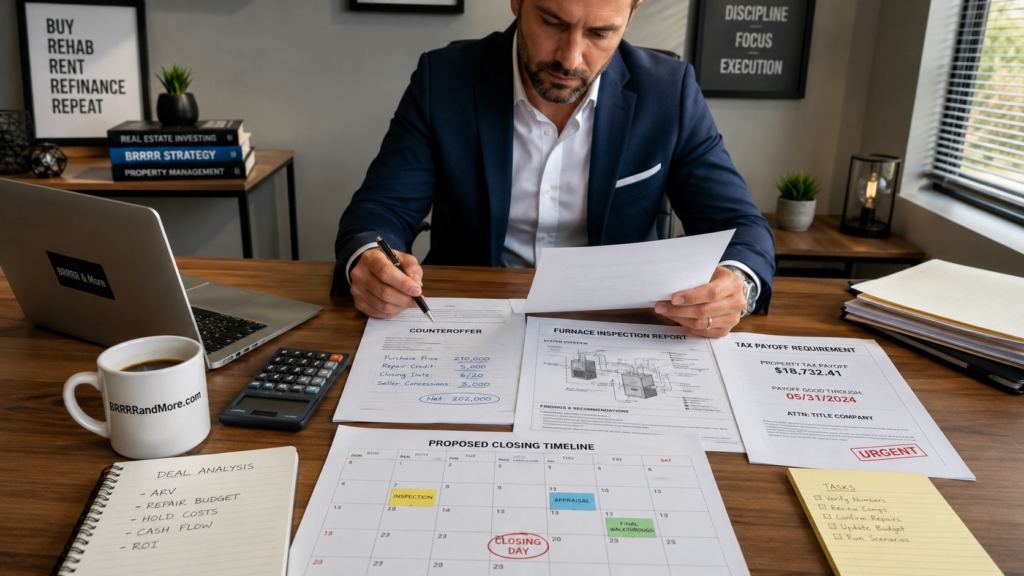
You make an offer on a property that appears to have solid BRRRR potential. The seller counters, but there is a complication: the seller wants to close sooner than your lender can comfortably accommodate.
You may be able to accelerate the loan by paying off a personal tax debt. Doing so would require you to commit significant cash before closing. Meanwhile, the house has a furnace that is approximately 25 years old and appears close to failure. The seller also wants a substantial earnest money deposit.
The property may still be a good opportunity. The danger is that urgency causes you to solve the seller’s timing problem by accepting financial and property risks that should have been investigated or negotiated.
Good BRRRR due diligence tells you which problems can be priced, which can be contractually protected, and which should stop the purchase.
Start by Separating the Problems
This counteroffer contains four distinct issues:
- The seller’s preferred closing date
- Your tax debt and financing readiness
- The condition of the furnace
- The amount and refundability of the earnest money
Treating them as one crisis makes it easier to concede too much. You could agree to the earlier closing, pay the debt, post a large deposit, and accept the furnace—only to discover another repair or financing problem later.
The seller appears to value speed and certainty. You need enough time to complete financing and investigate the property without putting an unreasonable amount of cash at risk.
That creates a possible negotiation: give the seller credible evidence that you can close, but do not promise a date or waive protections until the financing and property risks are understood.
First Confirm What the Lender Actually Requires
Before responding to the counteroffer, speak directly with the lender. Do not rely on a general statement that the tax debt “needs to be paid.”
Ask for a written explanation of:
- The exact debt creating the issue
- Whether a tax lien has been recorded
- Whether a full payoff is required
- Whether an approved payment agreement would qualify
- Which documents will prove the issue is resolved
- How long verification will take
- Whether the payoff will reduce required reserves or cash to close
Current Fannie Mae guidance on debts paid before closing distinguishes between different tax-debt situations. For example, delinquent federal taxes on an installment agreement may need to be paid in full when there is evidence of a recorded federal tax lien in the county where the financed property is located.
The practical lesson is not that every tax debt must be paid. It is that the lender must identify the requirement before you send money.
A Payoff Can Create a Second Financing Problem
Suppose you have $85,000 available:
- $38,000 for acquisition and closing
- $30,000 for rehabilitation
- $7,000 for holding costs
- $10,000 for contingency and reserves
If the lender requires a $15,000 tax payoff, you no longer have a fully funded $85,000 BRRRR plan. You have $70,000 available for the property.
You may qualify for the mortgage while leaving the project undercapitalized.
Before paying the debt, determine whether you can still close, replace the furnace, complete the rehabilitation, carry the property, and survive a refinance shortfall. Loan approval is not the same as having enough money to finish the BRRRR.
Decide What the Furnace Changes
A 25-year-old furnace deserves attention, but its age alone does not determine the negotiation.
ENERGY STAR recommends considering replacement when a furnace or boiler is more than 15 years old. That does not prove this unit is unsafe or nonfunctional, but it supports treating it as a likely near-term capital expense.
Have the system evaluated by a qualified HVAC contractor. You need more than an assurance that “it still works.” The evaluation should clarify whether the unit is safe, whether repairs are economical, whether venting or ductwork needs attention, and what replacement would cost.
Then compare the finding with your original underwriting.
When the Furnace Supports a Renegotiation
A price reduction or credit may be reasonable when you initially believed the system was serviceable and the inspection reveals a material defect, unsafe condition, or imminent replacement need.
The CFPB’s home inspection guidance notes that buyers may negotiate who pays for necessary repairs, depending on the contract and market conditions. An inspection contingency may also preserve cancellation rights when the results are unacceptable.
Your actual rights depend on the signed contract and local law.
When It Should Remain in Your Budget
If the furnace age was visible before the offer and your rehab budget already included replacement, presenting it as a surprise may weaken your position.
You can still include it in the complete economics, especially if the seller is asking you to accept a faster closing or larger deposit. The stronger argument is that the seller is requesting additional timing and financing risk, so the overall package must still make sense.
Measure the Cash at Risk Before Closing
The proposed tax payoff and earnest money should be viewed together because both require cash before you own the property.
Before increasing the deposit, confirm:
- Who will hold the money
- Which contingencies protect it
- When those contingencies expire
- Whether any portion becomes nonrefundable
- What happens if the lender misses the date
- What happens if title or inspection problems appear
- Whether an extension changes the deposit’s status
A large deposit is not automatically reckless. A large deposit with clear financing, inspection, appraisal, and title protections may be safer than a smaller deposit that becomes nonrefundable almost immediately.
The contract language matters more than the headline amount.
Negotiate by Exchanging Risk
The seller is asking for something valuable: speed.
If meeting that request requires you to pay debt sooner, compress due diligence, or risk more earnest money, you should receive something valuable in return.
That might be:
- A lower purchase price
- A seller credit
- A realistic financing period
- Adequate inspection access
- An extension right for documented lender or title delays
- Earnest money protected through defined milestones
- Seller responsibility for a specified repair
- Flexibility on another term important to the seller
The goal is not to win every issue. It is to avoid stacking all the risk on your side.
A reasonable business response might be: you are prepared to move promptly, provide lender documentation, schedule inspections immediately, and post meaningful earnest money—but only with a workable closing date and protections for financing, title, and material defects.
Your agent or real estate attorney should translate those points into contract language appropriate for the jurisdiction.
Should the Seller Replace the Furnace?
For a BRRRR investor, seller-completed repairs are not always preferable.
A seller under deadline pressure may select the least expensive equipment or contractor. The replacement may not address ductwork, venting, permits, or other issues important to your rental plan.
You may prefer to control the work after closing.
A price reduction lowers the property basis but does not provide cash for the repair. A seller credit may preserve cash at closing, although lender limits and permitted uses apply. Requiring replacement before closing may be appropriate if the furnace must function for financing, insurance, or immediate habitability.
Choose the remedy that solves the actual problem.
Recalculate the Entire Deal Before You Answer
Once the lender and HVAC contractor provide reliable information, rerun the analysis.
Include the revised purchase price, tax payoff, closing costs, furnace replacement, remaining rehab, contingency, holding costs, earnest money exposure, expected rent, conservative refinance proceeds, and capital remaining after refinance.
Also test a delayed refinance and lower appraisal.
The deal should not depend on the furnace being the only surprise or the refinance returning every dollar you expect.
Know When the Deadline Should End the Deal
You should be prepared to slow down or walk away when:
- The lender will not confirm the tax requirement.
- The payoff eliminates essential reserves.
- The deposit becomes nonrefundable before major due diligence is complete.
- The seller restricts inspection access.
- Title problems remain unresolved.
- The revised project no longer supports the expected rent or refinance.
The seller may have a legitimate reason for the deadline. That does not make it your obligation.
The Best Negotiation Protects the Full BRRRR
Closing is only the first step. You still need enough cash and flexibility to renovate, lease, refinance, and operate the property.
In this scenario, the correct first move is not to argue about the furnace. It is to confirm what the lender requires and determine what paying the tax debt does to your project capital.
Then inspect the property, price the furnace and other repairs, review the earnest money protections, and negotiate timing and economics as one package.
That is effective BRRRR due diligence: not avoiding every imperfect property, but refusing to let urgency turn a solvable deal into an underfunded one.